Improving Financial Stewardship in Churches: 2026 Guide
Last Updated: October 21, 2026
Why Improving Financial Stewardship in Churches Starts With the Heart
Financial stewardship is about much more than balancing a budget, paying bills, or preparing financial reports. For churches, it is about faithfully managing the resources God has entrusted to their care so they can fulfill their mission and serve their communities.
Throughout my career in financial leadership, I have learned that accurate financial records are essential, but they are only the beginning. What truly matters is how leaders use that information to make wise decisions, protect their ministries, and plan for the future.
Churches face financial challenges that are different from those of traditional businesses. Giving can fluctuate throughout the year. Ministry needs often exceed available resources. Pastors and board members may find themselves making significant financial decisions without the benefit of experienced financial leadership.
The good news is that improving financial stewardship does not require a church to become overly focused on money. It requires establishing sound financial practices that support the ministry rather than distract from it.
In this guide, I want to share practical steps church leaders can take to strengthen financial accountability, align their budgets with their mission, and build a foundation for sustainable ministry growth.
Key Takeaway Financial stewardship in churches is the intentional, accountable management of all resources God entrusts to a congregation, carried out with transparency and aligned to mission. It is a leadership responsibility shared by pastors, boards, and finance teams.
Stewardship as a Spiritual Practice, Not a Finance Task
Before discussing budgets, financial reports, or internal controls, we need to understand the biblical foundation of stewardship.
Scripture reminds us:
"Moreover it is required in stewards, that a man be found faithful." — 1 Corinthians 4:2 (KJV)
Everything a church receives is entrusted to it for a purpose. Financial stewardship is the responsibility of managing those resources faithfully, transparently, and in a manner that honors God.
This responsibility extends beyond the pastor or finance committee. It includes everyone entrusted with financial decisions, from the individual counting Sunday offerings to the board approving a major ministry initiative.
I believe one of the most important distinctions church leaders can make is recognizing that stewardship and fundraising are not the same thing.
Fundraising focuses on obtaining resources. Stewardship focuses on how those resources are managed once they have been received.
Both have their place in ministry, but strong stewardship should never depend on whether a church is experiencing financial abundance or financial difficulty.
Faithful stewardship is a year-round responsibility, not a response to a financial crisis.
When church leaders demonstrate consistency, integrity, and accountability, they create an environment where generosity can flourish and ministry can grow.
Aligning Your Church Budget With Mission and Values
Every church has a mission. Your budget should reflect that mission. Unfortunately, many church budgets are developed by taking the previous year's expenses, making a few adjustments, and hoping the available income will cover the result.
While historical financial information is an important starting point, it should not be the only factor guiding your budget.
A ministry-focused budget begins with a different question:
What has God called our church to accomplish, and how can we responsibly allocate our resources to support that calling?
Start With Ministry Priorities
Before developing the annual budget, church leadership should identify its priorities for the coming year.
These might include:
Supporting local and international missions.
Strengthening children's and youth ministries.
Expanding community outreach.
Maintaining church facilities and equipment.
Providing discipleship and educational opportunities.
Supporting pastoral staff and ministry operations.
Once these priorities have been established, leadership can evaluate how financial resources should be allocated.
This process helps ensure that financial decisions are intentional rather than simply repeating past spending patterns.
Understand the Difference Between Fixed Costs and Ministry Investments
Every church has ongoing financial obligations. Salaries, utilities, insurance, facility maintenance, and administrative expenses are necessary to keep the ministry operating.
However, those expenses also affect the amount available for additional ministry activities.
For example, a church may have a substantial annual budget, but much of that money may already be committed to operational costs.
Understanding this distinction helps leaders make realistic decisions about new programs, staffing, and expansion opportunities.
It also encourages thoughtful discussions about whether current spending continues to support the church's mission.
For a deeper look at this process, I encourage you to read our article on aligning nonprofit budgets with organizational missions.
Build Flexibility Into the Budget
A church budget should provide direction without becoming so rigid that leadership cannot respond to changing circumstances.
Unexpected building repairs, shifts in giving, or new ministry opportunities may require adjustments.
The goal is not to predict every expense perfectly.
The goal is to establish a financial plan that supports informed decisions throughout the year.
How to Monitor a Church Budget Without Drowning in Reports
One of the most common financial management challenges I see is treating the annual budget as a document that gets approved and then set aside.
A budget is only useful when leadership regularly compares the plan with what is actually happening.
Your budget should be a living financial management tool, not simply an annual requirement.
Review Financial Performance Monthly
At a minimum, church leaders should receive monthly financial reports that provide a clear picture of the church's financial position.
These reports should include:
Actual income compared with budgeted income.
Actual expenses compared with budgeted expenses.
Significant differences between planned and actual spending.
Current cash balances and available operating funds.
Giving trends and potential financial concerns.
However, receiving financial reports is not the same as understanding them.
A financial statement may show that contributions are below budget, but it does not automatically explain why or what leadership should do about it.
This is where financial analysis becomes valuable.
Understand the Story Behind the Numbers
Suppose your church budgeted $50,000 in contributions for a particular month but received only $42,000.
That represents an $8,000 shortfall.
The important questions are not limited to identifying the difference.
Leadership should also ask:
Is this a temporary fluctuation or part of a larger trend?
How does giving compare with the same period last year?
Are certain contributions seasonal?
Will the shortfall affect upcoming financial obligations?
Should planned spending or future projections be adjusted?
These questions turn financial reports into meaningful leadership tools.
Create a Simple Financial Dashboard
I encourage churches to consider developing a concise financial dashboard for their leadership teams.
A useful dashboard might include:
Financial Indicator | What It Helps Leadership Understand |
|---|---|
Total contributions | Whether giving is meeting expectations |
Budget versus actual | Where income and spending differ from the plan |
Cash available | Whether the church can meet upcoming obligations |
Operating reserves | How much financial protection the church has |
Restricted fund balances | Resources committed to specific purposes |
Giving trends | Whether contributions are increasing, declining, or remaining stable |
Not every board member needs to review every transaction.
They do need enough meaningful information to exercise responsible oversight.
Establish a Consistent Reporting Schedule
I recommend establishing three levels of financial review.
Monthly: Review income, expenses, cash balances, budget variances, and any immediate concerns.
Quarterly: Evaluate giving trends, operating reserves, restricted funds, and progress toward financial goals.
Annually: Review overall financial performance, evaluate the effectiveness of financial policies, complete the appropriate financial review or audit, and establish priorities for the next budget cycle.
Consistency is more important than producing complicated reports.
A clear report that leadership understands and reviews regularly is far more valuable than a lengthy financial package that no one knows how to interpret.
Pro Tip Ask your bookkeeper to prepare a monthly budget variance report that highlights significant differences between actual and budgeted income and expenses. But don’t stop at identifying the differences. Take time to understand why they occurred and what they mean for your church’s financial health. A report showing five significant variances with clear explanations and recommended actions is far more valuable than fifty unexplained numbers. The goal isn’t simply to report what happened. It’s to give church leadership the information needed to make wise financial decisions.
Church Internal Controls: Protecting the Flock's Generosity
Churches are built on relationships, trust, and shared faith.
Those qualities are essential to ministry, but they should never replace sound financial controls.
In fact, I believe financial controls are one of the ways a church demonstrates respect for the generosity of its congregation.
Internal controls are the policies and procedures designed to protect financial resources, ensure accurate recordkeeping, and reduce opportunities for mistakes or misuse.
They also protect the people entrusted with handling church finances.
Separate Financial Responsibilities
One of the most important principles of financial accountability is segregation of duties.
Whenever possible, no single person should control an entire financial transaction from beginning to end.
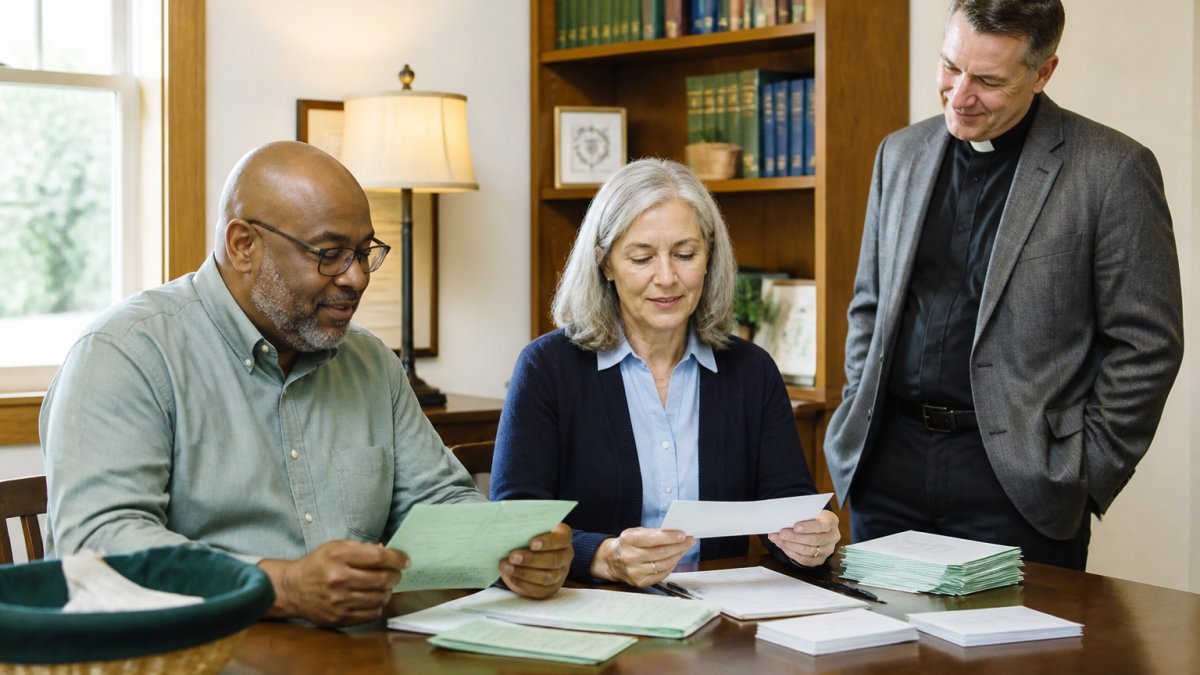
For example, the same individual should not be solely responsible for receiving contributions, recording them, depositing the funds, and reconciling the bank account.
A healthier process divides these responsibilities among multiple individuals.
Smaller churches may have limited staff and volunteers, making complete separation difficult. In those situations, additional oversight can help compensate for the limitations.
Establish Practical Financial Safeguards
Every church should consider implementing these foundational controls:
Two-person offering counts: Have at least two unrelated individuals count and document physical contributions.
Prompt deposits: Establish procedures for securely handling and depositing contributions without unnecessary delays.
Expense approvals: Require appropriate authorization before purchases and payments are made.
Supporting documentation: Maintain invoices, receipts, and other documentation for expenditures.
Monthly bank reconciliations: Reconcile all bank accounts and have someone independent of the preparation process review the results.
Payment authorization limits: Establish written approval requirements based on the size and nature of expenditures.
Restricted fund oversight: Ensure contributions designated for specific purposes are properly recorded, monitored, and spent.
These controls do not need to create unnecessary bureaucracy.
They should be appropriate for the church's size, staffing, and financial activity.
Trust and Accountability Work Together
I have seen organizations become overly dependent on one trusted individual who understands every aspect of their finances.
That person may be dedicated, capable, and completely honest.
However, relying on one individual without appropriate oversight creates unnecessary risk.
It also places an unfair burden on that person.
Strong financial systems allow responsibilities to be shared, transactions to be verified, and leadership transitions to occur without disrupting the ministry.
Financial accountability is not an expression of distrust. It is an expression of responsible stewardship.
Churches preparing for an external financial review may also find our church financial audit preparation checklist helpful.
Watch Out Trust should never replace accountability. Even the most dedicated church staff members and volunteers benefit from financial safeguards. When one person handles every aspect of a financial transaction without independent oversight, both the church and that individual are exposed to unnecessary risk. Strong internal controls protect honest people just as much as they protect financial resources.
Church Cash Flow Forecasting for Irregular Giving
A church can have a balanced annual budget and still experience cash flow problems.
This happens because income and expenses do not always occur at the same time.
Church giving often fluctuates throughout the year. Some congregations experience stronger contributions near year-end, while others see seasonal declines during summer months or holiday periods.
Meanwhile, expenses such as payroll, insurance, utilities, and loan payments continue regardless of when contributions arrive.
This is why cash flow forecasting is so important.
Understand the Difference Between a Budget and a Cash Flow Forecast
A budget outlines expected income and expenses over a defined period.
A cash flow forecast estimates when money will actually be received and when payments must be made.
Both are necessary, but they answer different questions.
Your budget asks:
Are we planning to operate within our available resources?
Your cash flow forecast asks:
Will we have enough available cash to meet our obligations when they come due?
A church needs to understand both.
Develop a Rolling Cash Flow Forecast
I recommend beginning with a forecast covering the next three to six months.
Start by identifying:
Expected contributions based on historical giving patterns.
Recurring expenses such as payroll and utilities.
Scheduled insurance payments and other periodic obligations.
Planned ministry events and outreach activities.
Major facility repairs or capital purchases.
Debt payments and other financial commitments.
Then compare expected cash receipts with anticipated payments.
This process can help identify potential shortages before they become emergencies.
Use Conservative Assumptions
One of the biggest mistakes an organization can make is developing financial projections based on its most optimistic expectations.
A strong giving month does not necessarily mean the same level of contributions will continue.
Forecasts should be grounded in historical information, known commitments, and reasonable assumptions.
They should also be updated as new information becomes available.
The objective is not to eliminate uncertainty.
It is to give leadership enough advance notice to make thoughtful decisions.
A Practical Example of Why Cash Flow Matters
Imagine a church with an annual operating budget of $600,000.
That averages $50,000 per month, but contributions don't necessarily arrive evenly throughout the year.
Suppose the church expects to receive only $35,000 in contributions during July while its regular monthly obligations total $48,000.
That creates a temporary cash shortfall of $13,000.
Even if annual contributions eventually meet the church's budget, leadership still needs a plan to cover July's obligations.
A cash flow forecast allows the church to anticipate that shortfall months in advance.
Leadership can then evaluate available unrestricted cash reserves, adjust the timing of discretionary expenditures, or take other appropriate steps without making rushed decisions.
The goal of cash flow forecasting isn't to predict the future perfectly. It's to prepare wisely for what may lie ahead.
Church Restricted Funds Management and Operating Reserves
Not all money held in a church's bank accounts is available for general operations.
This is an important distinction that can easily be overlooked when leadership focuses primarily on total cash balances.
A church may appear financially healthy based on its bank balance, but that number alone does not tell the whole story.
Some funds may be restricted by donors for specific purposes, while others may have been set aside by the governing board for future needs.
Understanding these differences is essential for making responsible financial decisions.
Understand Donor-Restricted Contributions
Some donors contribute funds for a particular ministry, project, or purpose.
For example, a donor may give specifically toward:
International missions.
A building project.
Benevolence assistance.
Youth ministry.
A designated community outreach initiative.
When a donor places a restriction on a contribution and the church accepts it, those resources must be used in accordance with the applicable restriction.
This is different from funds that church leadership has internally designated for a particular purpose.
Donor-restricted funds carry obligations that cannot simply be removed by a board vote.
If a church receives $100,000 specifically for a building project, those funds cannot automatically be used to cover payroll or other general operating expenses.
Even when the church experiences financial difficulties, leadership must honor the donor's intentions and applicable legal requirements.
Understand Board-Designated and Unrestricted Funds
Not all funds set aside for a specific purpose are donor-restricted.
Sometimes a church's governing board decides to allocate unrestricted resources toward a future project or financial goal.
For example, the board might designate $50,000 for future building maintenance or equipment replacement.
These are generally considered board-designated funds.
Unlike donor-restricted contributions, board-designated funds typically remain under the governing board's authority.
The board may be able to change or remove the designation through an appropriate approval process.
Unrestricted operating funds, on the other hand, are available to support the church's general operations and ministry activities, subject to its financial obligations and policies.
Understanding these categories helps church leaders distinguish between money that is legally restricted, money that has been internally designated, and money available for current operations.
Maintain Accurate Fund Accounting
Churches should establish accounting procedures that allow them to identify and report restricted contributions separately from unrestricted operating funds.
At a minimum, leadership should be able to determine:
How much has been received for each restricted purpose.
How much has been spent.
What funds remain available for that purpose.
Whether expenditures comply with donor restrictions.
Which funds have been designated by the board.
How much unrestricted cash is available to support operations.
One particularly important principle is that restricted resources should not be treated as available operating funds simply because they are sitting in the same bank account.
For example, imagine a church has $250,000 in its bank accounts.
At first glance, that may appear to be a strong financial position.
However, suppose:
$100,000 is restricted for a building project.
$50,000 is restricted for missions.
$40,000 has been designated by the board for future facility repairs.
That leaves $60,000 that has not been restricted or designated for those purposes.
Even then, leadership must consider upcoming payroll, accounts payable, and other financial obligations before determining how much cash is truly available.
A healthy bank balance does not necessarily mean a church has healthy operating cash flow.
Accurate fund accounting provides the clarity leadership needs to make responsible financial decisions while honoring the intentions of donors.
If a restricted purpose can no longer be fulfilled, leadership should obtain appropriate guidance regarding donor consent and applicable legal requirements before redirecting those funds.
Establish an Operating Reserve
Operating reserves provide financial stability when unexpected circumstances arise.
For example, reserves can help a church navigate:
A temporary decline in giving.
An emergency facility repair.
Unexpected operating expenses.
Delays in receiving anticipated contributions.
Other financial challenges that could disrupt ministry operations.
Many organizations use three to six months of operating expenses as an initial reserve-planning benchmark.
However, the appropriate amount depends on the church's financial circumstances.
A church with unpredictable contributions, significant facility responsibilities, or limited access to other financial resources may need a larger reserve.
The important step is to establish a reasonable target and develop a plan to work toward it.
Operating reserves should generally consist of resources available for operating needs, rather than donor-restricted funds committed to unrelated purposes.
Reserves Are Not a Lack of Faith
I believe this distinction is especially important for Christian ministries.
Planning for unexpected financial challenges does not mean leadership lacks faith in God's provision.
It means leadership is taking its stewardship responsibilities seriously.
Proverbs 21:5 reminds us that diligent planning leads toward abundance.
Building reserves allows a church to respond to challenges without immediately cutting essential ministry activities or making rushed financial decisions.
Reserves should never become an end in themselves.
Their purpose is to protect the church's ability to continue serving.
Faithful stewardship means trusting God while responsibly managing the resources He has already provided.
Pro Tip Don’t evaluate your church’s financial health based solely on its bank balance. Ask your finance team to prepare a report showing donor-restricted funds, board-designated funds, and unrestricted operating cash separately. Then compare available operating cash with financial obligations. The question isn't simply, "How much money do we have?" It's, "How much money is actually available to support our ministry's ongoing operations?"
Building a Culture of Generosity and Shared Financial Leadership
Financial stewardship should not be the responsibility of one person or department.
Healthy financial leadership requires cooperation among pastors, ministry leaders, financial personnel, and the governing board.
Each has a distinct role to play.
When those responsibilities are clearly defined, church leaders can focus on their individual areas of responsibility while working together toward a common mission.
The Pastor's Role
Pastors provide spiritual leadership and help the congregation understand biblical principles of generosity and stewardship.
They also help ensure that financial decisions remain connected to the church's mission.
However, pastors should not be expected to personally manage every financial detail.
A pastor's primary calling should not be overshadowed by bookkeeping, bank reconciliations, or the day-to-day administration of financial systems.
Instead, pastors should have access to reliable financial information and trusted individuals who can help them understand the financial implications of ministry decisions.
The Finance Team's Role
Bookkeepers, accountants, and finance personnel maintain the records and processes necessary for accurate financial reporting.
Their responsibilities may include:
Recording contributions and expenses.
Reconciling financial accounts.
Maintaining supporting documentation.
Preparing financial statements.
Tracking restricted funds.
Supporting budget preparation and reporting.
These responsibilities are essential.
However, accurate bookkeeping alone does not necessarily provide the strategic financial guidance leadership may need.
A church can have perfectly reconciled bank accounts and still struggle to understand its financial position or plan for future ministry needs.
The Governing Board's Role
The church's governing board, elders, trustees, or finance committee provides oversight and accountability according to the church's governance structure.
Responsibilities may include:
Approving the annual budget.
Reviewing financial performance.
Establishing financial policies.
Evaluating significant financial commitments.
Monitoring operating reserves.
Ensuring appropriate financial accountability.
Board members should ask questions and seek explanations when financial information is unclear.
However, they should not be expected to personally manage daily accounting activities.
Effective oversight requires understanding the financial information presented and using it to make responsible decisions.
The Value of Strategic Financial Leadership
This is where I believe many churches experience an important gap.
They may have someone maintaining accurate financial records and a board reviewing financial statements, but no one is consistently helping leadership understand the broader financial implications of its decisions.
For example, a bookkeeper can report that the church has $200,000 in its bank accounts.
A strategic financial leader goes further.
How much of that money is restricted? What financial obligations are coming due? How much cash is needed to maintain operations? Can the church responsibly move forward with a new ministry initiative?
These are the questions that help transform financial information into responsible decisions.
Bookkeeping tells you what has happened. Strategic financial leadership helps you understand what it means and plan what comes next.
Churches do not necessarily need a full-time CFO to benefit from this level of guidance.
A fractional CFO advisory relationship can provide experienced financial leadership while allowing church staff and pastors to remain focused on their primary responsibilities.
Pro Tip Give Every Financial Leader a Clear Responsibility Strong financial stewardship begins with clearly defined roles. Your bookkeeper should know who approves expenditures. Your finance committee should know which reports it needs to review. Your pastor should have access to meaningful financial information without being responsible for managing every transaction. And someone should be responsible for helping leadership understand what the financial information means for the church's future. When responsibilities are clear, accountability improves and ministry leaders can focus on the work God has called them to do.
Communicate Financial Information With Transparency
Congregations entrust churches with their financial gifts because they believe in the ministry's mission.
Church leaders have a responsibility to honor that trust through appropriate financial transparency.
Transparency does not mean every member needs access to every financial transaction or confidential record.
It means providing meaningful information that demonstrates how resources are being managed and how they support the church's work.
Share Financial Information in Understandable Terms
Many congregation members do not have accounting or financial management backgrounds.
Presenting detailed financial statements without explanation may leave them confused rather than informed.
Instead, consider providing a straightforward financial summary that answers questions such as:
How much did the church receive during the reporting period?
How were those resources used?
Did spending align with the approved budget?
What ministry activities were supported?
Are there significant financial challenges or upcoming needs?
The information should be accurate, consistent, and appropriate for the church's governance and reporting commitments.
Connect Financial Stewardship With Ministry Impact
Financial reporting becomes more meaningful when people understand what their generosity has helped accomplish.
Rather than only reporting that a particular amount was spent on outreach, leadership might explain how those resources supported families, community programs, or mission partners.
This helps the congregation see the relationship between financial stewardship and ministry outcomes.
It also reinforces an important truth:
The purpose of sound financial management is not simply to protect money. It is to make responsible ministry possible.
A Step-by-Step Annual Stewardship Plan for Church Leaders
Improving financial stewardship is not something a church accomplishes through one meeting or one new policy.
It requires an ongoing commitment to planning, accountability, and financial review.
An annual stewardship plan can help leadership establish a consistent rhythm while ensuring financial decisions remain aligned with the church's mission.
The following example assumes a calendar-year budget. Churches operating on a different fiscal year can adjust the timing accordingly.
Step | Timing | Key Action |
|---|---|---|
1. Evaluate financial performance | First quarter | Review prior-year results and identify improvements |
2. Establish mission priorities | Second quarter | Align financial planning with ministry goals |
3. Develop the annual budget | Third quarter | Prepare realistic financial projections |
4. Plan stewardship communication | Third quarter | Strengthen transparency and generosity education |
5. Approve the annual budget | Fourth quarter | Finalize financial plans and obtain approvals |
6. Monitor and adjust | Monthly | Review results and respond to changing conditions |
Step 1: Evaluate the Previous Year's Financial Performance
Recommended Timing: First Quarter
Begin by reviewing the church's financial performance from the previous year.
This review should include:
Comparing actual income and expenses with the approved budget.
Evaluating significant budget variances.
Reviewing cash flow and operating reserve balances.
Confirming restricted fund balances and expenditures.
Completing appropriate year-end accounting procedures.
Arranging an independent financial review or audit when required or appropriate.
The purpose is not simply to determine whether the church ended the year with a surplus or deficit.
It is to understand what happened financially, identify opportunities for improvement, and use those lessons to guide future decisions.
Step 2: Establish Ministry Priorities
Recommended Timing: Second Quarter
Before developing the next annual budget, church leadership should evaluate its ministry priorities.
Consider questions such as:
Which ministries are having the greatest impact?
Are there programs that need additional financial support?
Are current financial commitments sustainable?
What new ministry opportunities should be considered?
Are there financial risks that could affect future ministry activities?
These discussions should involve appropriate ministry leaders, financial personnel, and governing board members.
The goal is to ensure that financial planning begins with the church's mission rather than simply repeating the previous year's budget.
Step 3: Develop the Upcoming Annual Budget
Recommended Timing: Third Quarter
Once ministry priorities have been established, leadership can begin developing the upcoming year's financial plan.
This process should include:
Reviewing historical giving trends.
Establishing reasonable contribution projections.
Evaluating staffing and operational expenses.
Reviewing ministry and departmental budget requests.
Planning for facility maintenance and capital needs.
Evaluating debt obligations and other financial commitments.
Considering operating reserve goals.
I encourage churches to develop budgets using realistic financial assumptions rather than relying on overly optimistic giving projections.
A responsible budget should support ministry growth while recognizing the financial resources available.
Step 4: Plan Financial Communication and Stewardship Education
Recommended Timing: Third Quarter
Financial stewardship is strengthened when congregations understand how their generosity supports the church's mission.
Church leadership should establish a communication plan that may include:
Regular financial updates to the congregation.
Annual giving statements.
Ministry impact reports.
Biblical teaching on generosity and stewardship.
Updates on major ministry initiatives.
Clear communication about significant financial needs.
These communications should be consistent, transparent, and focused on the church's mission.
Generosity should never be presented solely as a response to financial difficulties.
Instead, stewardship education should help congregation members understand the biblical responsibility and joy of supporting the work God has entrusted to their church.
Step 5: Approve and Communicate the Annual Budget
Recommended Timing: Fourth Quarter
Before the new fiscal year begins, the proposed budget should be reviewed and approved according to the church's governance structure.
This process should include:
Reviewing the assumptions used to develop the budget.
Confirming that planned spending aligns with ministry priorities.
Evaluating anticipated cash flow.
Reviewing significant financial commitments.
Confirming operating reserve goals.
Obtaining the required leadership or board approvals.
Once approved, leadership should communicate an appropriate financial summary to the congregation.
The objective is not to overwhelm members with accounting details.
It is to help them understand how the church plans to use its resources to support ministry.
Step 6: Monitor Financial Performance and Make Adjustments
Recommended Timing: Monthly, Throughout the Year
Financial stewardship does not end when the annual budget is approved.
Church leadership should review financial performance regularly and make adjustments when circumstances change.
Monthly reviews should include:
Actual income and expenses compared with budget.
Significant financial variances.
Cash flow projections.
Operating reserve balances.
Restricted fund activity.
Emerging financial risks or opportunities.
Quarterly reviews can provide a broader perspective on giving trends, ministry spending, and progress toward financial goals.
When financial conditions change, leadership should evaluate the situation and respond thoughtfully rather than waiting until a problem becomes urgent.
A financial plan is most valuable when it helps leadership make informed decisions throughout the year.
Make Financial Stewardship Part of Regular Leadership Conversations
The most effective stewardship plans are not necessarily the most complicated.
They establish clear responsibilities, reasonable deadlines, and regular opportunities for leadership to evaluate financial performance.
They also allow room for adjustments when circumstances change.
Financial stewardship should be integrated into the church's leadership process rather than treated as a separate administrative task.
When pastors, financial personnel, and governing boards work together, financial management becomes a tool that supports the church's mission.
Faithful stewardship is not about controlling every dollar. It is about managing God's resources with wisdom, accountability, and purpose.
When Your Church Needs More Than Bookkeeping
Many churches begin with a bookkeeper, volunteer treasurer, or accounting professional who manages their day-to-day financial records.
That arrangement may work well for basic financial administration.
However, as a church grows, its financial decisions often become more complex.
Additional staff, expanded ministry programs, multiple funding sources, facility projects, and increased financial commitments can create a need for more advanced planning and oversight.
Church leadership may begin asking questions such as:
Can we afford to hire another pastor or ministry director?
How much should we maintain in operating reserves?
Can we expand our outreach programs without jeopardizing existing commitments?
How should we evaluate a major building project?
What financial risks should we be preparing for?
How can we develop more meaningful financial reports for our board?
These are strategic financial questions.
They require more than recording transactions and preparing monthly statements.
How Laurel Spring Supports Church Financial Stewardship
I founded Laurel Spring because I believe churches and mission-driven organizations deserve access to experienced financial leadership that understands both their financial responsibilities and their mission.
Through our Kingdom Stewardship Advisory™ program, I work alongside church and nonprofit leaders to strengthen financial clarity, accountability, and long-term planning.
Our advisory approach focuses on helping leadership understand its financial position, establish practical financial systems, evaluate financial decisions, and plan responsibly for the future.
This may include support with budgeting, cash flow forecasting, financial reporting, restricted fund oversight, and strategic financial planning.
My goal is not to replace your pastor, board, or existing bookkeeping team.
It is to provide financial insight and guidance that helps them lead with greater confidence.
I also recognize that not every church is ready for ongoing CFO advisory services. That is one reason I am committed to sharing practical financial stewardship education through Laurel Spring.
Every church, regardless of size, can benefit from understanding how to manage its resources faithfully and responsibly.
Final Thoughts: Faithful Stewardship Strengthens Ministry
Improving financial stewardship in churches is not about making ministry operate like a corporation.
It is about ensuring that the financial resources entrusted to the church are managed with wisdom, integrity, and accountability.
A well-developed budget helps leadership align spending with ministry priorities.
Consistent financial reporting provides the information needed to make responsible decisions.
Strong internal controls protect both financial resources and the people entrusted with them.
Cash flow planning and operating reserves help churches prepare for uncertainty.
And transparent financial leadership strengthens trust throughout the congregation.
None of these practices replaces faith.
Instead, they provide a practical framework for carrying out the responsibilities that come with faithful stewardship.
I believe that when church leaders have financial clarity, they are better equipped to focus on what matters most: serving people, strengthening their communities, and advancing the mission God has placed before them.
If your church is ready to strengthen its financial leadership, I invite you to explore Laurel Spring's Kingdom Stewardship Advisory™ program and learn how we can support your ministry.
Frequently Asked Questions
Who controls the finances of a church?
Financial responsibility should be shared among church leadership, the governing board, and designated financial personnel. The specific responsibilities depend on the church's governance structure, bylaws, and financial policies. Pastors provide spiritual and ministry leadership, finance personnel maintain records and financial processes, and the governing board provides appropriate oversight. Clearly defined responsibilities and segregation of duties help protect the church and promote accountability.
What financial controls should a church have?
Churches should establish basic financial controls that include two-person offering counts, appropriate expense approvals, monthly bank reconciliations, supporting documentation, and segregation of financial duties. Written policies should also address reimbursements, credit card usage, financial authorization limits, and restricted contributions. Smaller churches may need alternative oversight procedures when staffing is limited. The objective is to create reasonable safeguards appropriate for the church's size and financial activity.
How should churches manage restricted funds?
Donor-restricted contributions should be recorded and tracked separately from unrestricted operating funds. Church leadership should maintain documentation of donor restrictions, monitor expenditures, and ensure that funds are used for their intended purposes. If a restricted purpose can no longer be fulfilled, the church should seek appropriate guidance regarding donor consent and applicable legal requirements before redirecting the funds. Accurate restricted fund reporting is essential for financial accountability and donor trust.
How can a church plan for irregular giving and cash flow?
Churches can improve cash flow management by developing a rolling forecast that projects expected contributions and anticipated payments. Historical giving patterns, seasonal fluctuations, recurring expenses, and planned ministry activities should all be considered. Reviewing and updating the forecast monthly allows leadership to identify potential shortages early and make adjustments before financial challenges become urgent.
How can a church improve financial accountability?
Financial accountability begins with clearly defined responsibilities, written policies, consistent reporting, and appropriate independent oversight. Churches should establish financial procedures that protect contributions, require proper authorization of expenditures, and provide leadership with accurate financial information. Regular budget reviews, independent review of bank reconciliations, and appropriate communication with the congregation can strengthen accountability. Ultimately, financial accountability is about honoring the trust placed in church leadership and ensuring resources are used responsibly.
How should church leaders monitor a church budget?
Church leaders should compare actual income and expenses with the approved budget at least monthly. These reviews should identify significant variances, evaluate giving trends, and consider the effect of financial changes on future ministry activities. Leadership should also review cash flow projections and operating reserves. A budget becomes a valuable management tool when it helps leaders make informed decisions rather than simply documenting financial activity.
What is the difference between a church bookkeeper and a fractional CFO?
A church bookkeeper is primarily responsible for maintaining accurate financial records, recording transactions, reconciling accounts, and supporting financial reporting. A fractional CFO provides strategic financial guidance to help church leadership interpret financial information, evaluate risks, develop forecasts, and make informed decisions. Both roles are valuable, but they serve different purposes. A fractional CFO can work alongside the church's existing bookkeeper or accounting team without requiring the church to employ a full-time chief financial officer.
How can a church improve financial transparency without overwhelming its congregation?
Church leaders can provide clear, understandable financial summaries that explain contributions received, resources spent, significant financial developments, and the ministry outcomes supported. The level of detail should be appropriate for the church's governance structure and commitments to its members. Regular communication, consistent reporting, and a willingness to answer reasonable financial questions can strengthen congregational trust without requiring the disclosure of confidential information.
How can church leaders tell whether their financial stewardship practices are effective?
Church leaders should evaluate whether financial reports are accurate and timely, spending aligns with ministry priorities, restricted funds are properly managed, and appropriate financial controls are functioning. They should also consider whether leadership has the information needed to make decisions, anticipate challenges, and plan for future ministry needs. Ultimately, strong financial stewardship supports the church's mission while protecting the resources entrusted to its care.